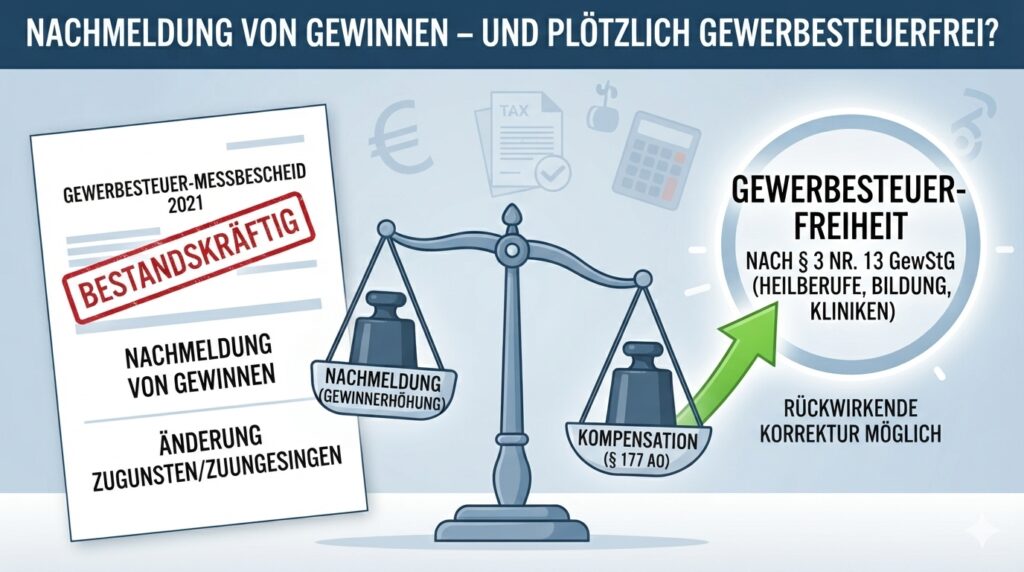
Reporting unreported profits—and suddenly exempt from trade tax?
In this example, a GmbH retroactively reported transactions that increased its profits to the tax office. In the course of this audit, it became apparent that the GmbH meets the requirements for trade tax exemption under Section 3(13) of the Trade Tax Act (GewStG) (e.g., healthcare professions, clinics, or educational institutions with specific exemption provisions). The trade tax assessment notice for the relevant year, 2021, is already final; a “normal” correction solely to enforce the exemption is no longer an option.
When is a retroactive, full trade tax exemption from trade tax still possible?
Full enforcement of the exemption requires that
- the trade tax assessment notice is still “pending” under procedural law (appeal period, provisional status, reservation of the right to review, and provisions governing amendments such as § 172, § 173, and § 175 of the German Fiscal Code [AO] apply) and
- the conditions for the trade tax exemption were already met in the year of origin and can be substantiated with supporting evidence.
In the absence of a relevant provision for correction, the trade tax liability incurred to date generally cannot be fully reversed.
Subsequent reporting of profits: Adjustments to the taxpayer’s disadvantage—and offsets to the taxpayer’s advantage (section 177 of the German tax code)
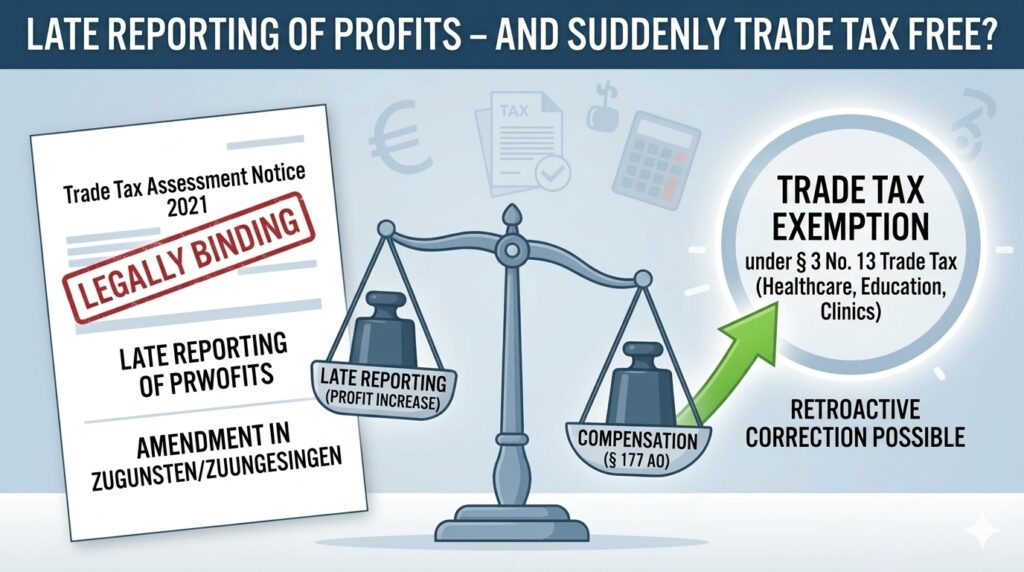
The subsequently reported circumstances that increase profits may—despite having become final—be addressed through:
- § 172(1)(2a) of the German Tax Code (AO) (Amendment with the taxpayer’s consent) or
- § 173(1)(1) of the German Fiscal Code (AO) (new facts)
…still need to be reported for trade tax purposes.
This constitutes a change “to the detriment” of the taxpayer. At this point, Section 177(1) of the German Fiscal Code (AO) provides for compensation:
- To the extent that the decision is amended due to the late filing, any substantive errors that cannot otherwise be corrected must also be corrected within the scope of this amendment.
- One such material error is the failure to apply the exemption from trade tax.
Consequence for the example case:
The trade tax assessment notice for 2021 remains in effect, but the trade tax exemption is granted for the additional income reported retroactively as part of the same amendment. This prevents the late filing from resulting in an additional trade tax burden, even though the GmbH is fundamentally exempt.
In summary
- A full retroactive exemption from trade tax is possible only in exceptional cases once the decision has become final.
- In the event of subsequent adjustments to profits, one should always examine whether compensation in favor of the taxpayer can be obtained under § 177 of the German Fiscal Code (AO), so that at least the “new” income remains subject to exemption from trade tax.
We would be happy to assist you. Contact us here.
Sources: s&w Steuerberatungsgesellschaft mbH, Unterberg & Unterberg Partner
Photo: AI-generated (Google)
Disclaimer: We assume no liability for the accuracy and completeness of the information. The information provided here does not constitute recommendations for action.
