Specialist blog: Taxes & Business

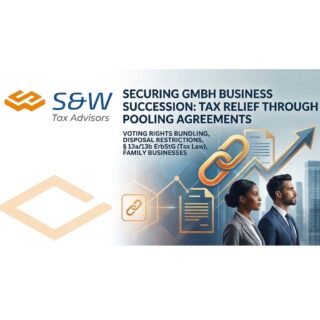
An infographic on business succession for limited liability companies (GmbH) produced by s&w Tax Consultancy, featuring the English text ‘Securing GmbH Business Succession Tax Relief through Pooling Agreements’, two business figures and symbols representing the pooling of voting rights.

Business Succession for GmbHs: Optimize Taxes Now

Business Succession for GmbHs in Family-Owned Businesses—Why Early Planning Is Crucial Many family business owners wish to transfer their GmbH shares to the next generation while they are still alive. A key tool for tax-efficient planning of business succession for GmbHs is the tax relief for business assets under Sections 13a and 13b of the German Inheritance Tax Act (ErbStG) [...]
Tax planning in a real-life case: How a debt waiver with a recovery clause and loss carry-back can be used to manage the restructuring of a GmbH. Read it now!

GmbH Crisis: Debt Waiver with Recovery Note – Act Now

Tax Planning During GmbH Crisis: Debt Waiver with Recovery Note and Loss Carryback—A Real-World Case Study Many growth- and research-intensive companies face the same problem in their early years: high development expenses, consistently negative results, and financing primarily through shareholder loans. The following anonymized case study of a German GmbH with a foreign parent company illustrates the income tax implications […]

A modern office with a view of the skyline, combined with the company logo ‘s&w’ and a graphic on the theme of business succession, depicting two crossed swords above documents relating to the Inheritance Tax Act (ErbStG) and the German High Court.

German High Court Ruling: Defend Your Business Succession Strategy Now

Business Succession: Planning Under the Sword of Damocles of the German High Court Ruling (BVerfG) The inheritance and gift tax benefits under Sections 13a and 13b of the German Inheritance Tax Act (ErbStG) have for years been among the key tools for tax-optimized business succession.  At the same time, ensuring a seamless business succession has become increasingly complex, as these […]

A practical case study on an on-site income tax audit at a medium-sized GmbH: Repeated special payments to the controlling shareholder-managing director give rise to discussions regarding established business practice, deemed remuneration and hidden capital contributions, with significant income tax risks. Drawing on Federal Fiscal Court (BFH) case law and a detailed analysis of shareholders’ resolutions, this article demonstrates when a claim to special payments that is relevant for income tax purposes actually arises, and how tax advisers can effectively avoid phantom wages and hidden capital contributions through proper remuneration documentation.

Wage Tax Audit: Special Payments to Shareholder-Managing Director

Case Study: Wage Tax Audit—Special Payments to Shareholder-Managing Director Recently, during wage tax audit (income) at one of our clients, a particularly practical case arose regarding the compensation of a controlling shareholder-managing director. The point of contention was the special payments made over many years (e.g., “Christmas bonus” or June/December payments)—and the question of whether these gave rise to an [...]
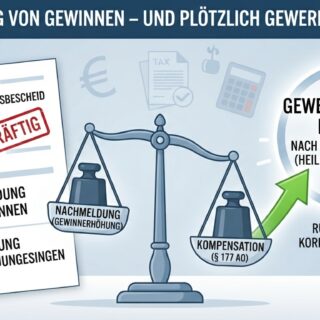
Infografik zum Thema Gewerbesteuerrecht: Eine Waagschale gleicht die „Nachmeldung von Gewinnen“ (Änderung zuungunsten) durch eine „Kompensation nach § 177 AO“ aus. Ein grüner Pfeil weist auf die Möglichkeit der rückwirkenden „Gewerbesteuerfreiheit nach § 3 Nr. 13 GewStG“ hin, während links ein Dokument mit dem Stempel „Gewerbesteuermessbescheid 2021 – Bestandskräftig“ zu sehen ist.

Trade tax exemption after revised profit declaration: options for GmbHs

Reporting unreported profits—and suddenly exempt from trade tax? In this example, a GmbH retroactively reported transactions that increased its profits to the tax office. In the course of this audit, it became apparent that the GmbH meets the requirements for trade tax exemption under Section 3(13) of the Trade Tax Act (GewStG) (e.g., healthcare professions, clinics, or educational institutions with […]

German Electronic Book-Keeping Relocation Penalty (relocation fee): Overview of new sanctions under Section 146(2c) AO for unauthorised relocation or failure to re-relocate electronic bookkeeping systems to Germany, including applicable conditions, fines from 2,500 to 100,000 euros, and practical implications for companies using digital bookkeeping.

Relocating Electronic Bookkeeping Abroad: Rules and How to Avoid Penalties

Relocating accounting operations abroad: regulations and how to avoid penalties German regulations on the relocation of electronic invoicing have become more flexible in recent years. Companies can now maintain and manage electronic books and records not only within the EU/EEA, but also in other countries, provided that the legal requirements are met. These include countries such as the USA, Switzerland […]

Unternehmensnachfolge planen: Zivil- und steuerrechtlich durchdachte Gestaltung der Nachfolge zur Minimierung von Pflichtteilsrisiken und Erbschaftsteuerbelastungen durch lebzeitige Übertragung, vorweggenommene Erbfolge und strukturierten Nachfolgefahrplan zur Sicherung der Unternehmenszukunft und des Familienfriedens, unter Nutzung von Gestaltungsspielräumen im Lichte der Rechtsprechung von BFH und Bundesverfassungsgericht.

Constitutional Risk: Why Business Owners Should Plan Their Succession Now

§13a Inheritance Tax Act 2026: Business succession – between tax relief and constitutional risk Business succession is not only a matter of family, leadership, and strategy, but also a key tax decision. Section 13a of the German Inheritance Tax Act (ErbStG) can significantly reduce the tax burden on business assets in the event of inheritance or a gift—provided that the […]

E-Rechnung ab 2025 in Deutschland: Grafik zu den neuen Pflichten für Unternehmer bei inländischen B2B-Umsätzen, Definition der E-Rechnung als strukturierte elektronische Rechnung nach § 14 UStG, Überblick über Übergangsregelungen bis spätestens 31.12.2027 (Papier- und sonstige elektronische Rechnungen mit Zustimmung, Umsatzgrenze 800.000 EUR), Anforderungen an Empfangsbereitschaft ab 1.1.2025 und an die Ausstellung von E-Rechnungen sowie Auswirkungen auf Vorsteuerabzug und Anpassung der Rechnungs- und Buchhaltungsprozesse.

E-invoicing: mandatory for businesses from 2025

E‑Invoicing from 2025: Requirements, Transitional Regime and Practical Impacts As an entrepreneur or service provider, you inevitably have to deal with invoices. However, starting from 2025, businesses must observe changes because of the e-invoicing obligation. This article deals with these innovations and further information. Paper invoices and e-invoices Invoices are part of day-to-day business for entrepreneurs, service providers and customers. […]

Inheritance in Germany: allowances to optimize German inheritance and gift taxes

Inheritance in Germany: allowances for less inheritance tax

Inheritance in Germany: allowances for less inheritance tax Usually, anyone who experiences a death in the family also deals with inheritance. In Germany, inheritance is subject to tax. However, there are allowances that vary depending on the degree of relatedness and the amount of the inheritance. These allowances make it possible to pay less levy. This article explains the various […]

GDPR Cookie Consent with Real Cookie Banner